Natural Rubber Weekly Report: Bottom Support and Rebound Pressure(Oct 22)
Natural Rubber Weekly Report: Bottom Support and Rebound Pressure
1. Natural Rubber Spot Market Analysis
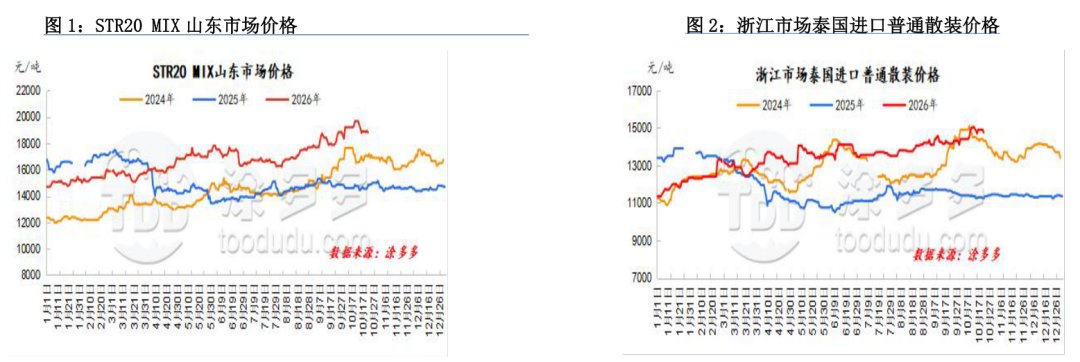
This week, natural rubber prices showed a clear downward trend. On the pressure side, as weather conditions improved both domestically and abroad, tapping disruptions eased, limiting the upward momentum of raw material procurement prices, and cost support continued to loosen. In terms of inventory, both Qingdao and social rubber inventories showed an accumulation trend, with supply pressure rising at the margin, further weakening the market’s bullish sentiment. However, support factors also exist. With downstream production gradually resuming, enterprises actively stocked up at low prices, and procurement demand warmed up, which may provide some support for the bottom of natural rubber prices. Overall, cost loosening and inventory accumulation exert pressure, but downstream low-price stocking provides bottom support. In the short term, rubber prices are likely to maintain a wide-range oscillation pattern.
This week, the natural latex market showed a weak adjustment pattern of "pressure above, support below." Pressure mainly came from supply improvement and demand resistance. In Hainan and Yunnan production areas, weather and tapping conditions improved, raw material prices lacked continued upward momentum, and upstream processing plants faced increased shipping pressure. On the demand side, downstream product enterprises showed strong resistance to high-priced raw materials, spot transactions with premiums were difficult to conclude, and the pace of goods circulation was slow, putting significant downward pressure on prices. Bottom support also exists. Current production area raw material and cost levels remain high, the cost-side support has not disappeared; coupled with a year-on-year contraction in Southeast Asian latex cargo arrivals, import replenishment is weak, supply-side pressure is limited, and price support below remains strong. Overall, under the long-short game, natural latex is likely to adjust weakly downward in the short term, but the downside is limited by cost and import contraction support, making deep declines unlikely for now.
Market Outlook:
1. Domestic production area rainfall improves, with rising output expectations;
2. Tire sample enterprise operating rates are expected to increase next week;
3. Qingdao inventory accumulation pace slows;
4. Macroeconomic atmosphere disturbances.
2. Natural Rubber Supply Analysis
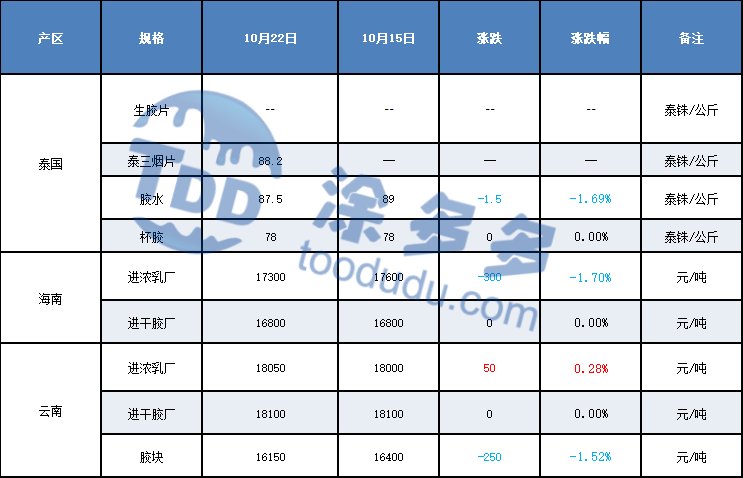
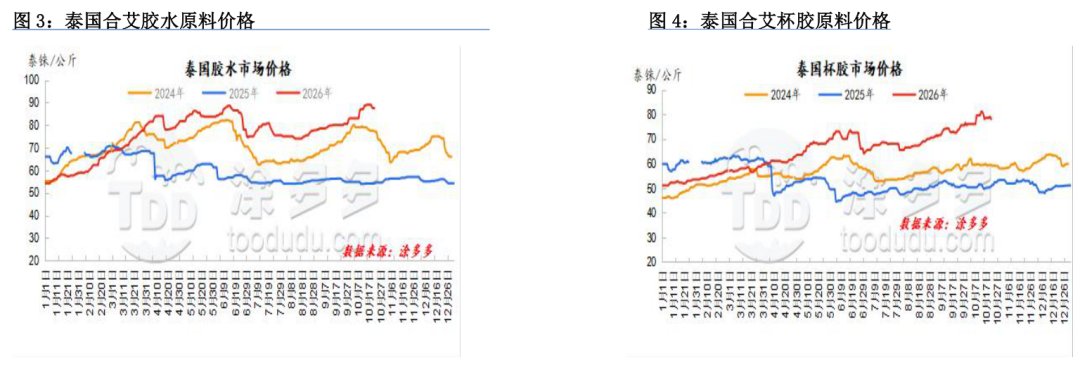
In Thailand, weather in the northeast improved, accelerating cup rubber release. Dry rubber processing plants maintained aggressive raw material procurement, while second-tier traders held back at low prices, limiting downside room for cup rubber. In the south, rainfall disruptions intensified, affecting tapping work. Latex plants showed limited willingness to purchase at higher prices, and latex prices fell slightly.
2.2 Vietnam Production Area
In Vietnam, early-week rainfall continued to cause disruptions, but weather improved toward the weekend. However, the production increase pace remained slow overall, with limited output recovery. Recurrent rainfall in multiple areas continued to interfere with tapping operations, and the supply-tight pattern persisted.
2.3 Yunnan Production Area
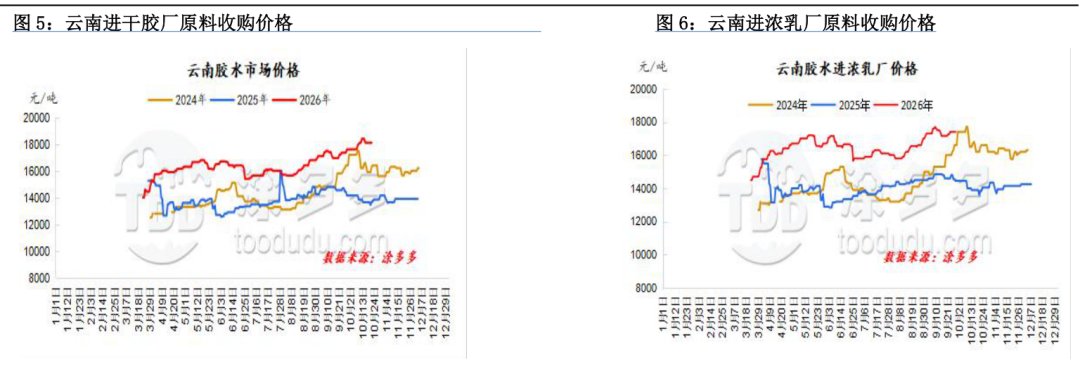
In Yunnan, weather continued to improve this week, with mostly cloudy skies and light rain, low rainfall, and increased effective tapping days. Xishuangbanna and other main production areas had favorable weather; only Lincang and Dehong had locally excessive cumulative rainfall, with limited impact on tapping. The production area is gradually approaching the end of the season, but new rubber output still maintains a steady upward pace.
2.4 Hainan Production Area
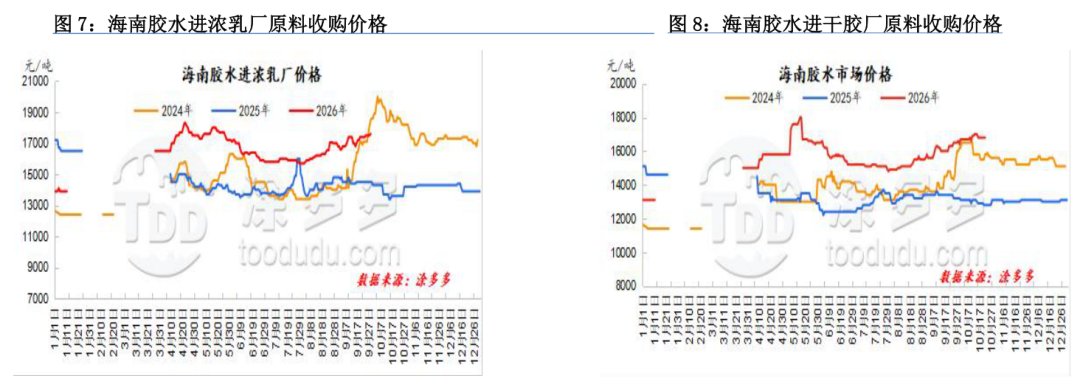
Hainan production area experienced irregular rainfall, increasing the impact on tapping operations. The peak production pace of raw materials slowed. Although futures traded weakly with a cautious market atmosphere, local processing plant production profits and orders remained satisfactory, with good raw material restocking demand. Despite rainfall, plants maintained aggressive purchasing at higher prices, supporting high latex prices.
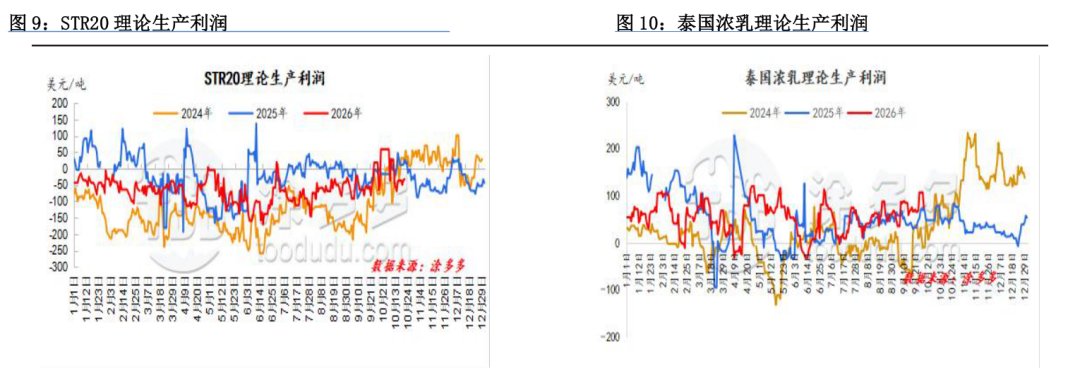
Thailand STR20 theoretical production profit improved week-on-week. During the period, cup rubber prices and Thai factory finished product quotes fell simultaneously, but raw material concessions were larger, reducing procurement costs. The theoretical processing profit of STR20 improved compared to the previous period.
3.2 Domestic Production Area: Hainan
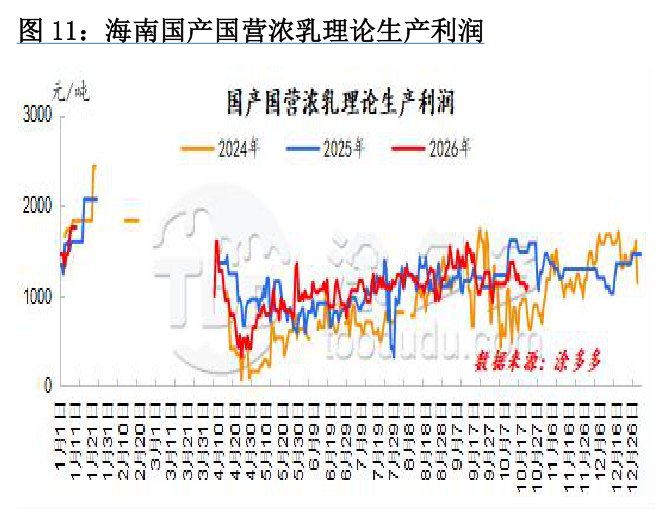
This week, Hainan state-owned concentrated latex theoretical production profit continued to decline. Raw material restocking demand was strong, with competitive bidding in the market. However, finished product spot price support was weak and showed a declining trend, dragging down production profits.
4.1 Dry Rubber Downstream
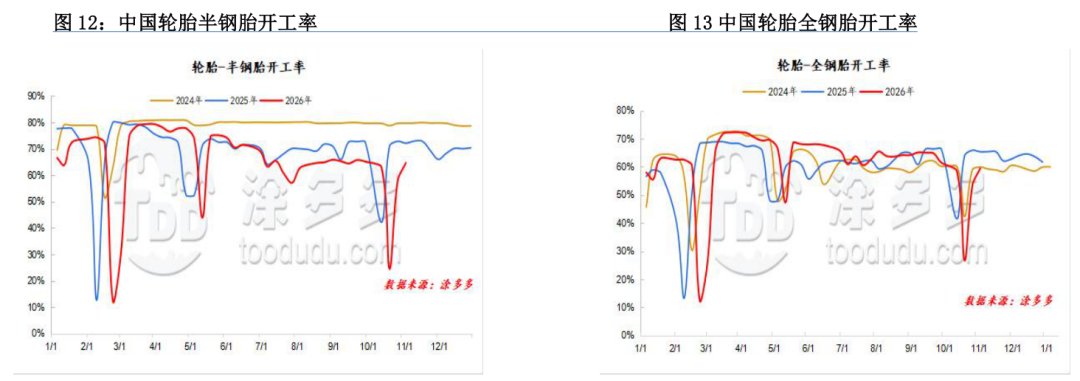
China semi-steel tire operating rate: 65%. China all-steel tire operating rate: 59%.
During the week, tire enterprises gradually resumed production scheduling, driving a significant increase in overall operating rates. However, as raw material prices remained high, tire enterprises implemented production controls, limiting the extent of operating rate increases.
4.2 Concentrated Latex Downstream
In North China, glove factory operating rates were around 50-60%. As temperatures dropped and the traditional "Golden September, Silver October" peak season approached, some factories launched resumption and production increase plans. Coupled with rising rubber prices during the week, the "buy on rises, not on falls" sentiment drove some factories’ demand to warm up periodically. However, due to prominent cost-side pressure, factories generally adopted a cautious attitude, purchasing only as needed in small quantities, with no large-scale stockpiling intentions.
In Wenzhou, foam factory operating rates were stable at around 50%. After finished product price increases, order follow-up remained unsatisfactory, with end-users purchasing mainly on a rigid-demand basis. Affected by high raw material prices, processing plant profit margins were narrow, and purchasing attitudes toward high-priced raw materials were cautious, mostly adopting a strategy of small-quantity restocking after price drops. Current factory raw material inventories were generally low, maintained at safe minimum levels.
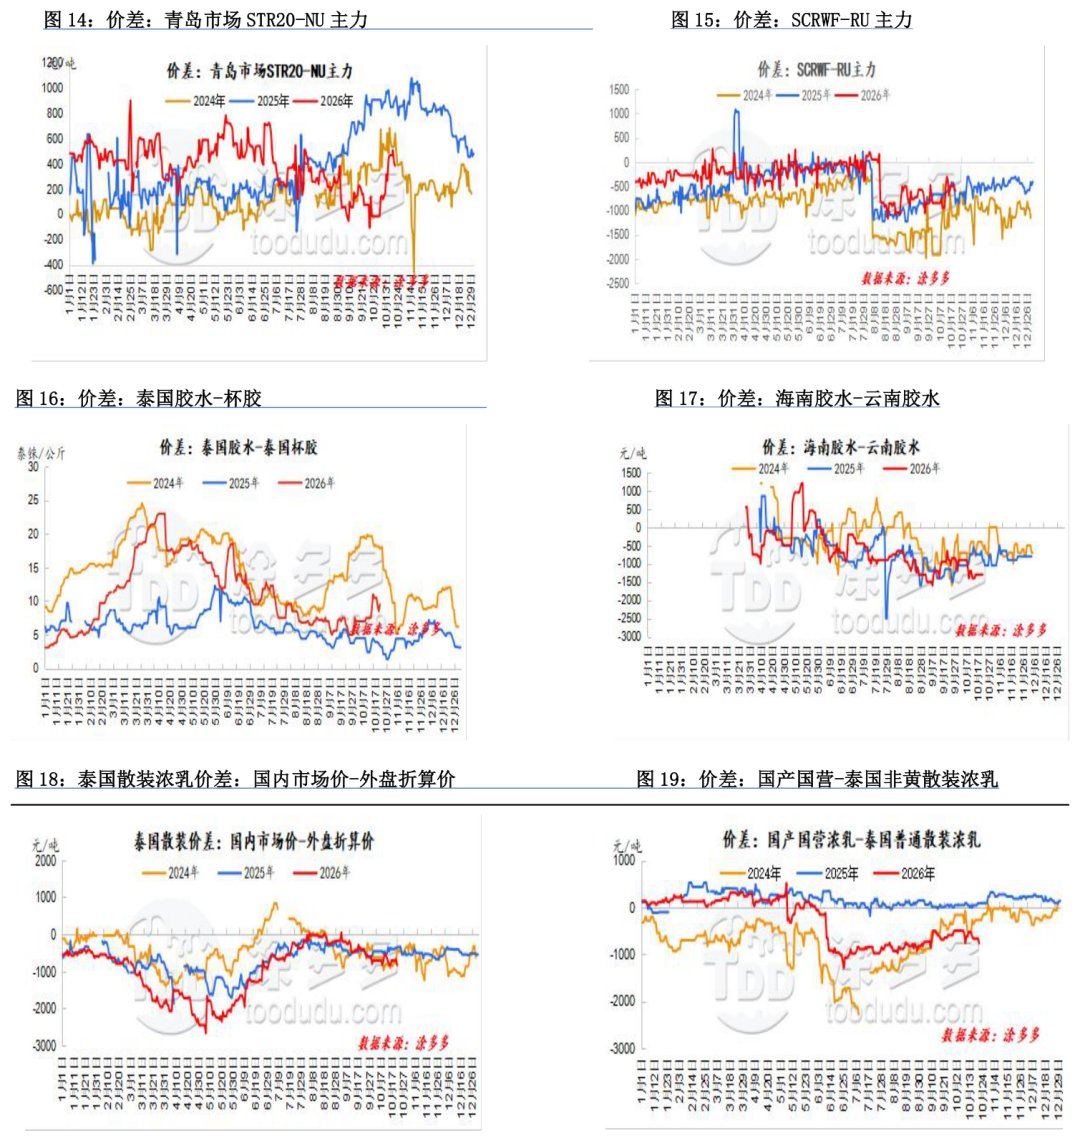
5. Natural Rubber Price Spread Statistics
Double Coin Tire: 350 Million Yuan Capital Increase to Chongqing Base Finalized, Shareholding Ratio Rises to 71.58%
Double Coin Tire Group recently completed the industrial and commercial registration change for its capital increase to the Chongqing production base. The capital increase totaled 350 million yuan, raising the Chongqing factory’s registered capital from 600 million yuan to 950 million yuan. Double Coin Tire Group’s shareholding ratio increased from 55% to 71.5789%, with other participating shareholders’ equity diluted accordingly. This is Double Coin’s sole investment in the Chongqing base, further concentrating control.
The Chongqing base is Double Coin’s core production platform for the southwest market and one of the group’s four major domestic tire manufacturing bases, primarily producing commercial vehicle tires with an annual capacity of 2.8 million units. This capital increase will supplement factory operating funds, support intelligent manufacturing upgrades, green technology improvements, and product structure optimization, consolidating Double Coin’s production capacity foundation in the western tire market.
Notably, this capital increase plan was approved back in 2019, with funds disbursed that same year, but the industrial and commercial registration change was delayed due to multi-shareholder coordination. With the equity adjustment finalized, Double Coin’s decision-making authority over the Chongqing factory has significantly strengthened, facilitating coordinated production planning, technology investment, and market strategy.
The domestic tire industry is currently in a structural adjustment period, with leading enterprises generally increasing base technology upgrade investments and optimizing regional capacity layout. Double Coin’s Chongqing investment will focus on energy conservation, carbon reduction, and production line upgrade projects, supporting stable domestic OEM and overseas export business operations.
Guizhou Tire Morocco Project Design Tender Finalized, Overseas Approval Becomes Last Hurdle Before Construction
Guizhou Tire’s subsidiary Qianjin Tire (Morocco), with an annual capacity of 6 million semi-steel radial tires in its smart manufacturing project, recently completed two design tenders, advancing the project to an executable stage.
According to the Guizhou Provincial Public Resources Trading Platform, the construction drawing design winning candidate was announced on October 8, with China Machinery & Industry United Engineering Corporation ranking first. The preliminary and process design (second round) tender result was announced on October 10, with China Chemical Industry Guilin Engineering Corporation winning the bid at 5.68 million yuan. The completion of both design stages means the project has the conditions to proceed further at the engineering preparation level.
However, the project has not yet entered substantial construction. Guizhou Tire stated on the investor interaction platform on October 16 that all domestic approval and filing procedures have been completed, and the company is now accelerating overseas-related approvals. Previously, the project’s wholly-owned subsidiary obtained the Enterprise Overseas Investment Certificate from the Guizhou Provincial Department of Commerce in August, and both the provincial SASAC approval and the provincial NDRC overseas investment project filing have been completed. In other words, the Morocco project is at a transitional point of "domestic procedures complete, awaiting overseas approval to commence construction."
The Morocco base is located in the Tanger Tech City, with a total investment of approximately 299 million USD (about 2 billion RMB), a construction period of two years, and projected average annual revenue of 180 million USD upon full production. This is Guizhou Tire’s second overseas production base after Vietnam, with products focused on semi-steel radial tires targeting the European, North American, and Southeast Asian markets.
In terms of location, Tanger Tech City is adjacent to the Tanger Med port, providing advantages in transport time and tariff costs for products entering the European market. The area has already attracted production capacity from multiple Chinese tire enterprises. With design tenders completed, whether the project can quickly transition to construction will depend on the pace of overseas approvals.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.
-
Titanium Product Market Quotation(Oct 22)9229
-
Carbon Black Weekly Report: Cautious Sentiment Prevails, Carbon Black Prices Remain Firm(Oct 22)7414
-
Natural Rubber Weekly Report: Bottom Support and Rebound Pressure(Oct 22)6063
-
Titanium Product Market Quotation(Oct 21)9185
-
Carbon Black Daily: Negotiations Stalled, High Prices Hard to Materialize(Oct 21)10009