Carbon Black Weekly Report: Cautious Sentiment Prevails, Carbon Black Prices Remain Firm(Oct 22)
Carbon Black Weekly Report: Cautious Sentiment Prevails, Carbon Black Prices Remain Firm
1.1 Carbon Black Market Price Analysis
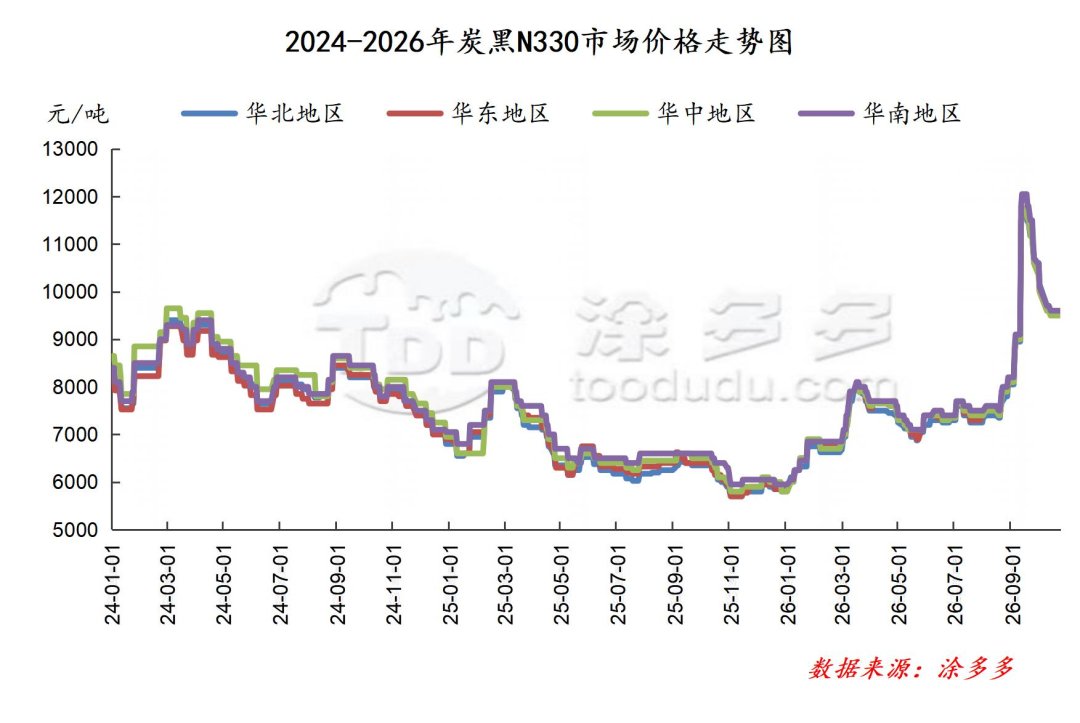
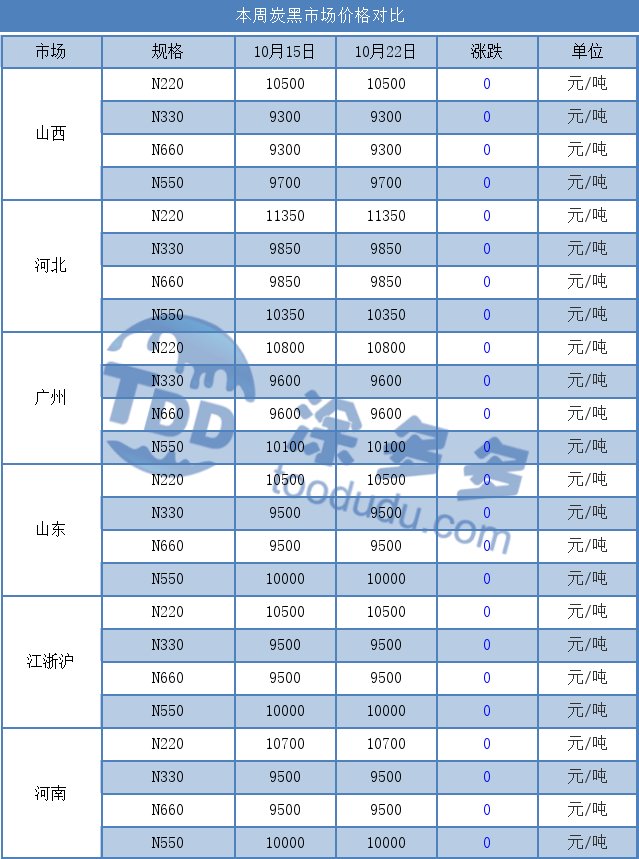
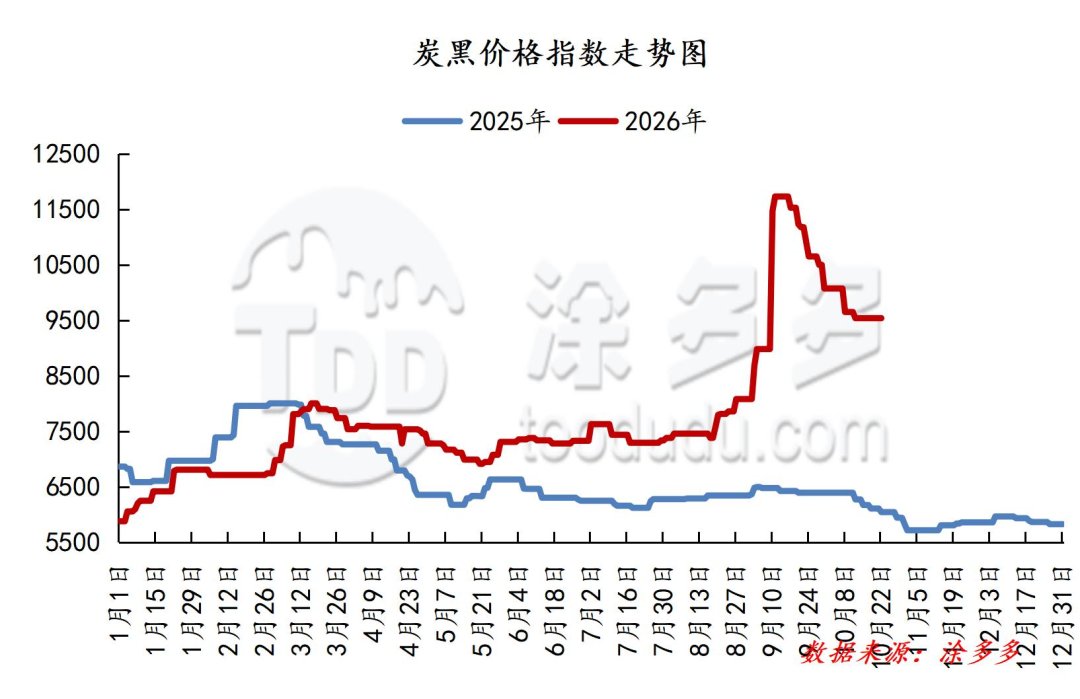
This week, domestic carbon black prices maintained a stable trend. As of Thursday, prices were: Shandong region 9,500 yuan/ton; Shanxi region 9,300 yuan/ton; Hebei region 9,850 yuan/ton; Guangzhou region 9,600 yuan/ton; Zhejiang region 9,500 yuan/ton. The negotiation atmosphere for new orders in the domestic carbon black market was moderate this week, with overall trading pace relatively flat. Both buyers and sellers mostly held a wait-and-see attitude.
Approaching the weekend, raw material coal tar prices were released one after another, with new order quotes showing both increases and decreases. The cost side remained at high levels, providing some favorable support for carbon black market prices, and enterprises showed limited willingness to lower prices. Although downstream wait-and-see sentiment was strong and procurement was not active, there was still certain rigid demand supporting the market, and no decline expectations emerged. Currently, the carbon black market mostly follows raw material market price trends for negotiations, and the overall performance remains firm in the short term.
2. High-Temperature Coal Tar Market
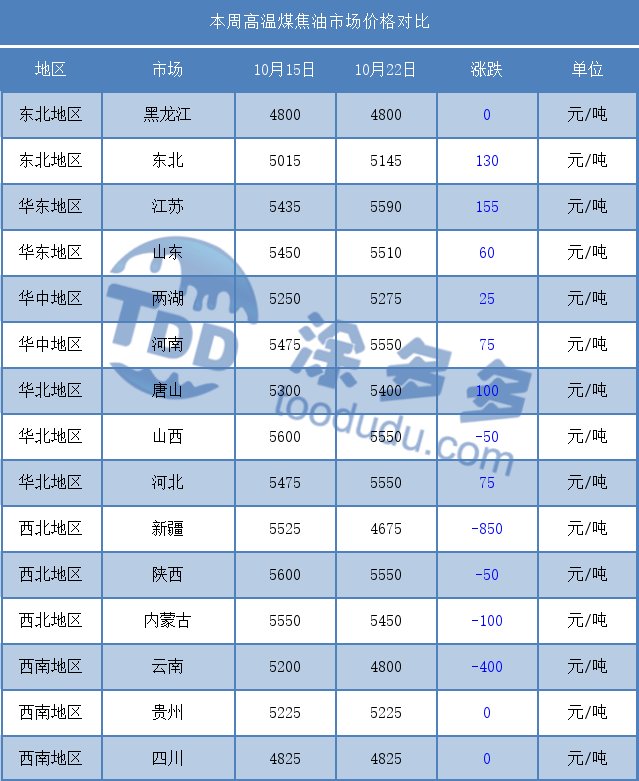
This week, the high-temperature coal tar market showed mixed trends. Approaching the weekend, new order prices for domestic high-temperature coal tar were released successively, presenting an overall mixed picture. As supply and demand conditions varied across regions, the upward pace diverged across areas since last week, leading to different profitability situations for downstream deep-processing enterprises. Entering this week, downstream factories in some regions showed strong resistance to high prices, with significantly increased bargaining pressure, dragging local prices lower. However, cost support remained, and the market ultimately presented a mixed pattern. Overall, the high-level oscillation pattern is difficult to change, and the short-term price center is expected to remain at a relatively high level.
3. Anthracene Oil Market
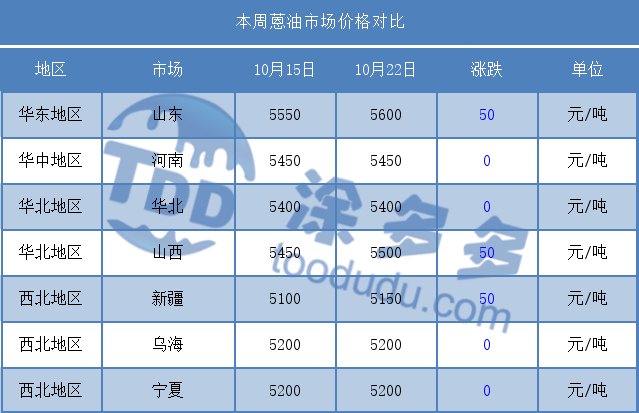
This week, the domestic anthracene oil market showed upward sentiment for new orders. From the cost side, raw material high-temperature coal tar new order prices were gradually released, mostly showing an upward trend, supporting anthracene oil suppliers’ quotation sentiment, and manufacturers showed limited willingness to concede on price. However, manufacturers mostly maintained a wait-and-see stance, with weak proactive quotation activity and limited new order guidance. From the demand side, the downstream carbon black market continued to press prices down, putting some pressure on anthracene oil prices, and the buyer-seller game remained deadlocked. Overall, cost-driven increases and demand-driven price suppression restrain each other, and the short-term anthracene oil market is expected to have limited volatility, maintaining a narrow range adjustment.
Market Outlook
Looking ahead to next week, raw material coal tar new orders show mixed trends, with the cost side continuing to oscillate at high levels, leading to significant cost pressure on carbon black. Therefore, carbon black new order quotes will remain at high levels, and downstream buyers’ rigid-demand purchasing pace remains unchanged. New order fluctuations are expected to be limited, with stable shipments.
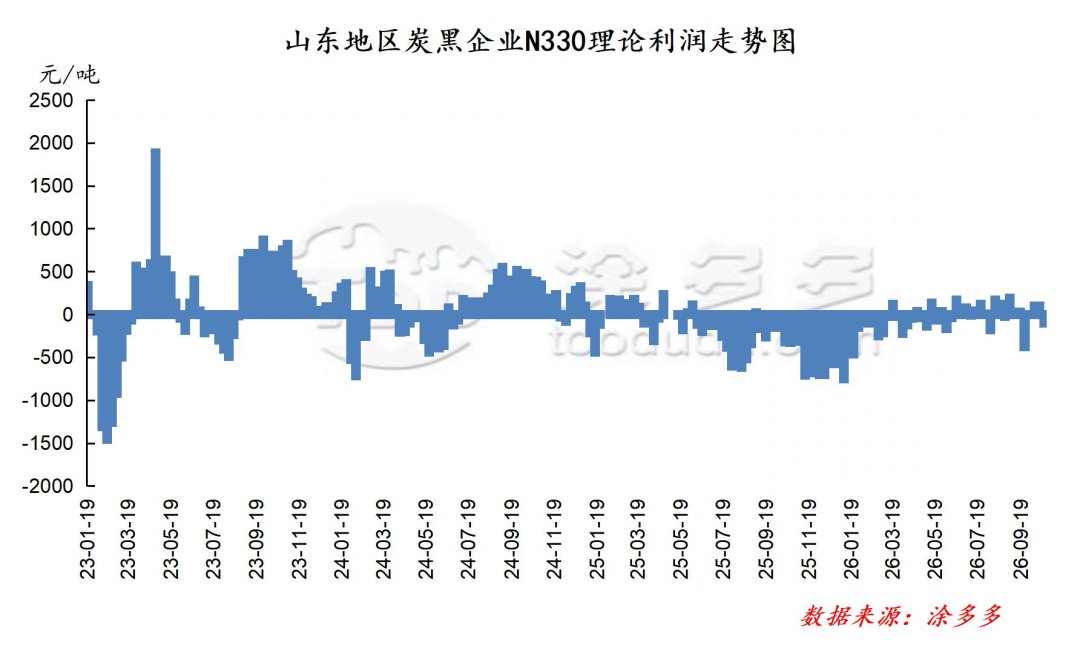
4. Carbon Black Industry N330 Profit Analysis
Taking Shandong region as an example, raw material coal tar prices remained temporarily stable, while carbon black new orders maintained stability, resulting in a theoretical loss for the carbon black market. As of now, the theoretical weekly profit of the carbon black industry is -95.5 yuan/ton, down 193 yuan/ton from the previous period.
5. This Week’s Market Operating Rate Statistics
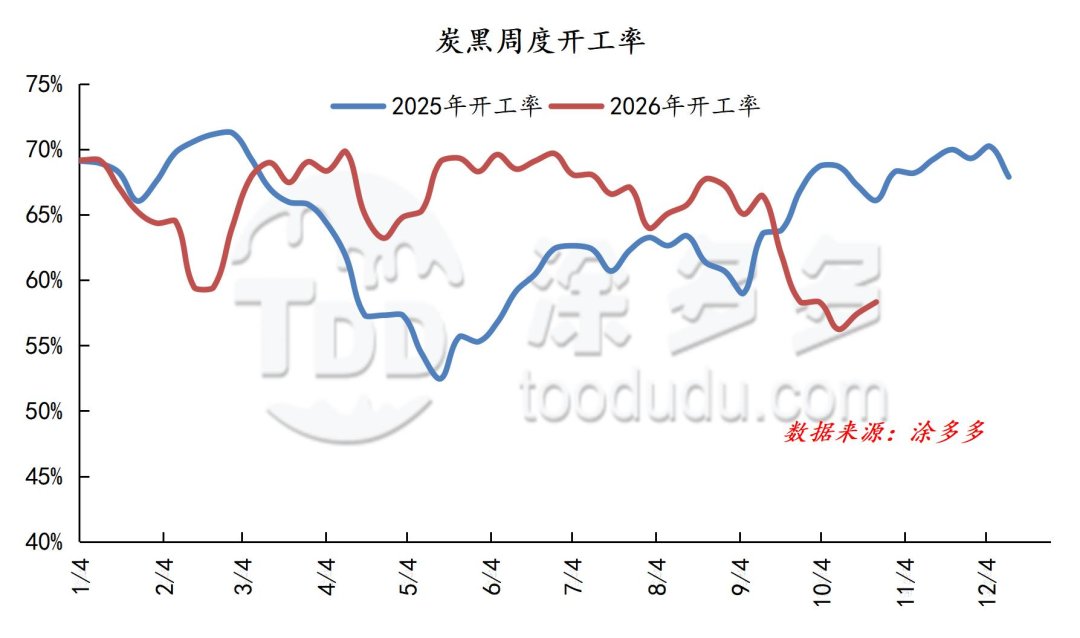
Domestic carbon black market sample enterprise operating rate: 58%.
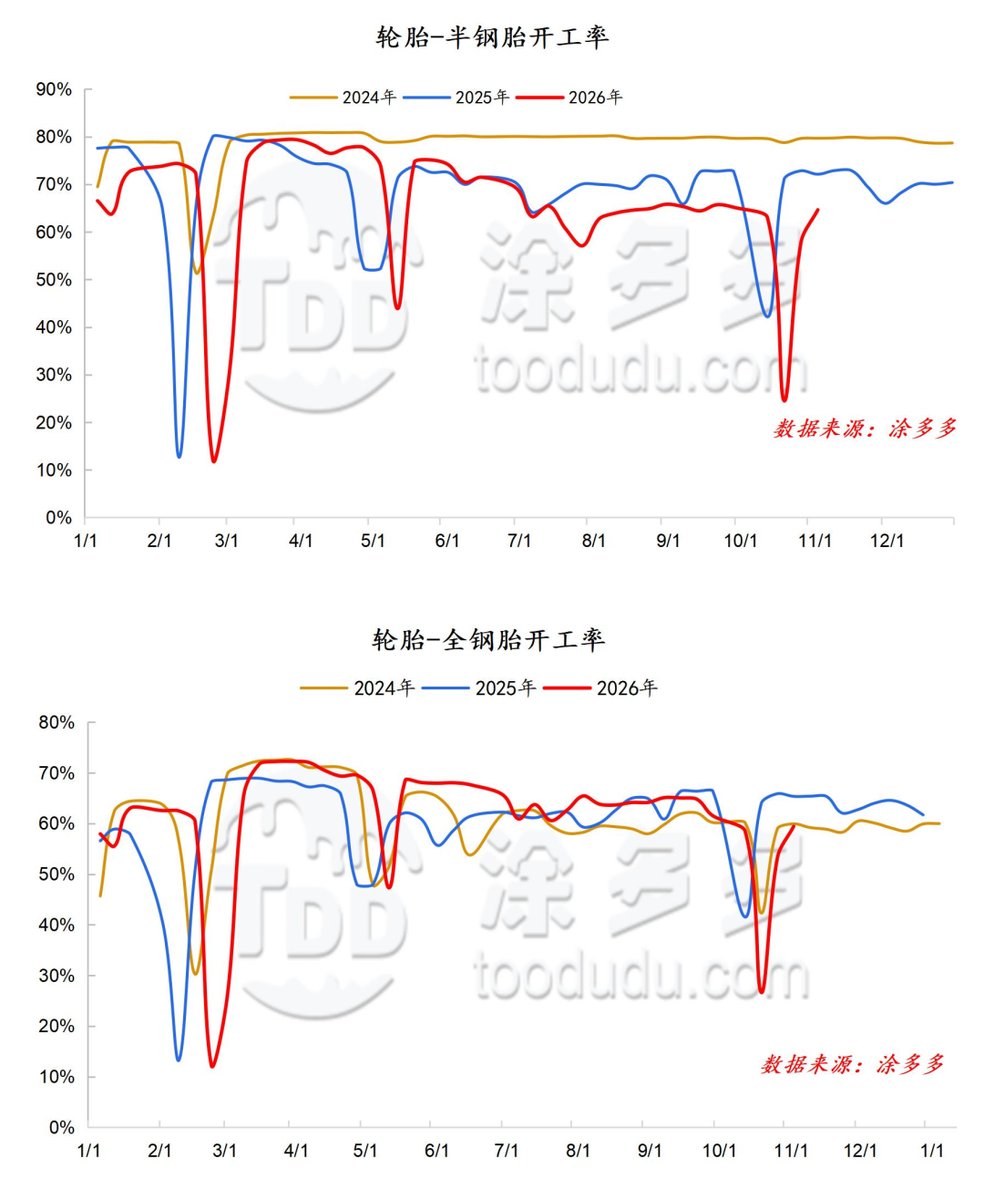
China semi-steel tire operating rate: 65%. China all-steel tire operating rate: 59%.
During the week, tire enterprises gradually resumed production scheduling, driving a significant increase in overall operating rates. However, as raw material prices remained high, tire enterprises implemented production controls, limiting the extent of operating rate increases.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.
-
Titanium Product Market Quotation(Oct 22)9238
-
Carbon Black Weekly Report: Cautious Sentiment Prevails, Carbon Black Prices Remain Firm(Oct 22)7430
-
Natural Rubber Weekly Report: Bottom Support and Rebound Pressure(Oct 22)6083
-
Titanium Product Market Quotation(Oct 21)9195
-
Carbon Black Daily: Negotiations Stalled, High Prices Hard to Materialize(Oct 21)10028