Carbon Black Daily Report: Sentiment Is Set, but Transactions Lag Behind(Nov 10)
November 11, 2026
TDD-Global
9191
Guide
Highlights at a glance
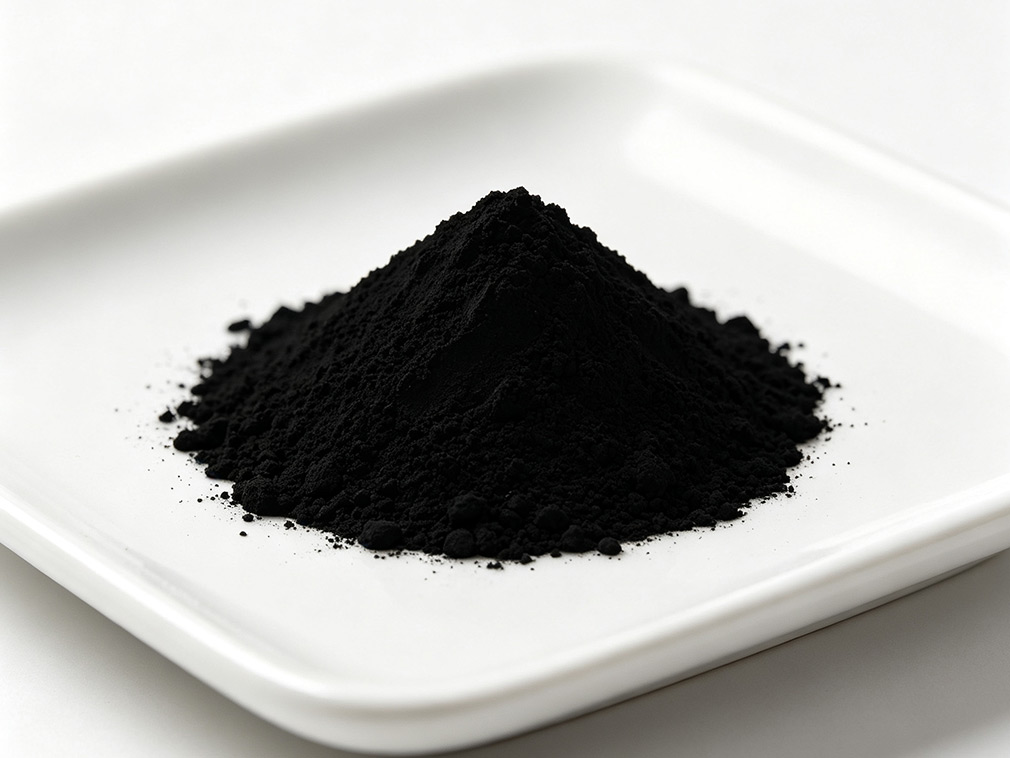
The November 10 Carbon Black Daily Report highlights stable price indexes across key markets, with no significant fluctuations noted in grades such as N220, N330, N660, and N550. Upstream raw material coal tar prices remain resistant to declines but exhibit a cautious outlook. Supply-side operating rates for carbon black production show minimal fluctuations as enterprises prepare for the heating season. Demand remains tepid, marked by slow purchasing activity, limited new orders, and weak buying sentiment. As trade sentiment remains flat, the outlook for the near term reflects consolidation and low engagement, with limited drivers from costs or demand to shift the market toward growth. TDD-Global offers unparalleled connections with verified suppliers and buyers worldwide, enhancing your procurement experience.
Carbon Black Daily Report: Sentiment Is Set, but Transactions Lag Behind
01 Carbon Black Index
According to TOODUDO estimates, the carbon black price index stood at 9,304 on November 10, unchanged from the previous trading day.
02 Carbon Black Market Prices
Prices below are tax-inclusive delivered prices in CNY per tonne.
|
Market
|
Grade
|
Nov 9 (CNY/t)
|
Nov 10 (CNY/t)
|
Change
|
|---|---|---|---|---|
|
Shanxi
|
N220
|
10,200–10,400
|
10,200–10,400
|
0
|
|
Shanxi
|
N330
|
9,400–9,600
|
9,400–9,600
|
0
|
|
Shanxi
|
N660
|
9,000–9,200
|
9,000–9,200
|
0
|
|
Shanxi
|
N550
|
9,000–9,200
|
9,000–9,200
|
0
|
|
Hebei
|
N220
|
10,800–11,000
|
10,800–11,000
|
0
|
|
Hebei
|
N330
|
9,400–9,600
|
9,400–9,600
|
0
|
|
Hebei
|
N660
|
9,400–9,600
|
9,400–9,600
|
0
|
|
Hebei
|
N550
|
9,900–10,100
|
9,900–10,100
|
0
|
|
Guangzhou
|
N220
|
10,500–10,700
|
10,500–10,700
|
0
|
|
Guangzhou
|
N330
|
9,300–9,500
|
9,300–9,500
|
0
|
|
Guangzhou
|
N660
|
9,300–9,500
|
9,300–9,500
|
0
|
|
Guangzhou
|
N550
|
9,800–10,000
|
9,800–10,000
|
0
|
|
Shandong
|
N220
|
10,200–10,400
|
10,200–10,400
|
0
|
|
Shandong
|
N330
|
9,200–9,400
|
9,200–9,400
|
0
|
|
Shandong
|
N660
|
9,200–9,400
|
9,200–9,400
|
0
|
|
Shandong
|
N550
|
9,700–9,900
|
9,700–9,900
|
0
|
|
Jiangsu–Zhejiang–Shanghai
|
N220
|
10,200–10,400
|
10,200–10,400
|
0
|
|
Jiangsu–Zhejiang–Shanghai
|
N330
|
9,200–9,400
|
9,200–9,400
|
0
|
|
Jiangsu–Zhejiang–Shanghai
|
N660
|
9,200–9,400
|
9,200–9,400
|
0
|
|
Jiangsu–Zhejiang–Shanghai
|
N550
|
9,700–9,900
|
9,700–9,900
|
0
|
|
Henan
|
N220
|
10,400–10,600
|
10,400–10,600
|
0
|
|
Henan
|
N330
|
9,200–9,400
|
9,200–9,400
|
0
|
|
Henan
|
N660
|
9,200–9,400
|
9,200–9,400
|
0
|
|
Henan
|
N550
|
9,700–9,900
|
9,700–9,900
|
0
|
03 Market Analysis
1. Upstream raw materials: Coal tar prices were CNY 5,560 per tonne in Shandong, CNY 5,550 per tonne in Shanxi, and CNY 5,560 per tonne in Hebei. The domestic high-temperature coal tar market is mainly in a wait-and-see mode. Supported by supply-demand fundamentals, the market faces some resistance to declines; prices are likely to run slightly weak, with limited room for a sharp drop.
2. Carbon black supply: The operating rate of sampled domestic carbon black enterprises edged up narrowly, with mixed changes across plants. As the heating season approaches, some enterprises have supply-security plans, and operating rates are expected to remain stable later on; the market will thus see large plants operating steadily and small plants running at low loads. Overall, operating-rate fluctuations are limited, with mainly narrow adjustments.
3. Downstream demand: Industry profitability is weak. Some enterprises operate at only around 50%–70% of capacity with low loads. A few mid-to-large plants perform adequately, producing mainly to order, but their product specifications are incomplete and some models are in tight supply.
04 Outlook
New orders in the domestic carbon black market are stabilizing and consolidating; trading sentiment is flat and overall activity is low. Early in the week, wait-and-see sentiment is strong, with buyers and sellers waiting for the outcome of raw-material order talks for guidance. Operations are cautious, and most on-market business consists of executing earlier orders, with insufficient follow-through on new orders. Downstream purchasing remains limited to essential-demand inquiries, the pace is slow, and willingness to buy at high levels is weak, leaving limited new-order volume. Positive factors are currently not evident; neither the cost side nor the demand side offers effective drivers, and market confidence is weak, so new orders are likely to run on the soft side.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.
Recommended for you
-
Titanium Product6792
-
Carbon Black Daily Report: Sentiment Is Set, but Transactions Lag Behind(Nov 10)9191
-
Natural Rubber Daily Report: Bulls and Bears Pull Against Each Other, Direction on Hold(Nov 10)8025
-
Titanium Product Market Quotation(Nov 9)8217
-
Carbon Black Daily Report: Essential Demand Holds the Floor, Price Suppression Continues(Nov 9)6188
January 29, 2026, 3:29 PM
August 21, 2024, 2:42 PM
August 21, 2024, 2:28 PM
August 21, 2024, 2:20 PM
August 21, 2024, 3:01 PM